Briefings

Goodhart’s Law: When Your Sustainability Metric Becomes a Liability

Where has Goodhart’s law turned your well-intentioned metric into a liability? If you lead a sustainability program, a reporting function, or an executive team that sets targets, the honest answer is probably: somewhere on your board slide already. You just haven’t found it yet.

The law

In 1975, Charles Goodhart, an economist advising the Bank of England, observed that any observed statistical regularity will tend to collapse once pressure is placed upon it for control purposes. The anthropologist Marilyn Strathern later sharpened his point into the sentence everyone quotes: “When a measure becomes a target, it ceases to be a good measure.”

Goodhart was writing about monetary policy. He could have been writing about sustainability, a field that runs on measures turned into targets: percentages, intensities, scores, and claims. And in sustainability, the collapse of the measure is no longer just an embarrassment. Since September 27, 2026, in the European Union it can be an illegal claim.

The percentage fell; the pile grew

Consider a company that reduces the virgin plastic in each unit it makes by 30% over ten years, and reports the reduction as a triumph. The report is accurate. The conclusion is not.

Do the multiplication nobody did. At 5% annual growth, ten years compounds to 1.63 times as many units. Per-unit plastic fell to 0.70 of its starting point. Multiply the two: total virgin plastic is up roughly 14%. The percentage fell. The pile grew.

Notice that nobody lied, and nobody gamed anything. The team hit its target honestly. The target was per unit, and the denominator moved. The denominator is the count underneath the percentage, the number of units the per-unit figure divides by, and at 5% growth it does not sit still. This is the form of Goodhart’s law that should worry executives most: not the cynical kind, where people cheat the number, but the innocent kind, where the number is accurate, audited, and faithfully reported, while the thing it was meant to describe goes the other way.

The target was per unit. The planet counts units.

The measure was never the point

A recycled-content target asks how much recycled polyester is in the jacket. A better question asks what the jacket is for. A designer who did the arithmetic on cost per wear, a €30 jacket worn five times costs €6 per wear; a €300 jacket worn three hundred times costs €1, reframed the problem entirely: this jacket needs to survive 300 wears. One question optimizes an input. The other examines the assumption underneath it.

Or take offset-based “carbon neutral” claims. The metric performed beautifully for a decade: targets set, offsets purchased, claims printed. The assumption underneath, that paying for reductions elsewhere is the same as reducing your own emissions, was never examined. The EU has now banned the claim outright. A target can be met, reported, and audited for years, and still end as a liability, because the belief it rested on was never true.

And there is no final, incorruptible metric waiting at the end of this search. Cost-per-wear can be gamed the moment it becomes a target, just as recycled content was. That is the law’s real lesson. The answer is not a better measure. The answer is examining what your measures assume.

Goodhart is the symptom; the belief is the disease

The standard telling of Goodhart’s law blames gaming, people optimizing the number instead of the work. In nearly fifty years inside this field, I have found the gaming to be the least of it. The measure usually fails earlier, at the moment it is chosen, because it is chosen inside a belief nobody has examined.

The per-unit target assumed the denominator would sit still. The recycled-content target assumed the material was the problem. The offset claim assumed someone else’s reductions were interchangeable with your own. Every metric on your dashboard is a belief wearing a number, and the belief, not the number, is where the risk lives.

This is also why the problem is about to get faster. The AI systems now drafting strategies, disclosures, and sustainability reports were trained on our reporting, decades of it, built on the same unexamined assumptions. Ask a model to help you hit the target and it will optimize against the gamed measure fluently, confidently, and at machine speed. Goodhart’s law used to operate at the speed of an annual report. It now operates at the speed of generation.

Audit your own metrics: five steps

  1. List the headline metrics. The handful of numbers on the board slide, the ones your sustainability performance is judged by.
  2. Name the denominator. For every percentage, ratio, and intensity figure, ask what it assumes will hold still: unit volumes, product mix, revenue, headcount. Denominators move. That movement is where the gap hides.
  3. Ask what the target rewards. Every target rewards some behavior and quietly punishes some other. If your people are rewarded for the number, what are they being punished for noticing?
  4. Follow the material. Compare each metric with the physical quantity it claims to describe: units, tons, wears, years of use. When the metric and the material disagree, believe the material.
  5. Ask the belief question. For each metric: what had to be assumed for this to be the right measure? Who examined that assumption, and when?

Steps one through four find discrepancies. Step five finds the cause. It is the step almost everyone skips, and the only one that prevents the next metric from failing the same way.

The diagnostic

Step five, done properly, is a discipline rather than a checklist. It is the work of the Belief Gap Diagnostic: a structured examination of the beliefs underneath an organization’s claims, targets, and AI-supported decisions, the distance between what the organization believes and what it can actually substantiate. That distance is the belief gap, and it is where regulators, journalists, and competitors will eventually look.

Your metrics are not lying to you on purpose. They are answering, faithfully, the questions they were built from. The question worth asking, before someone else asks it for you, is the one this post began with: what had to be assumed for that answer to be true?


*Ken Alston has spent nearly fifty years inside sustainability: twenty years at SC Johnson, seventeen alongside William McDonough and Michael Braungart, and nine years in independent practice. He keynotes on the assumptions hiding inside executive decisions, and runs the diagnostic that finds them before a regulator, a journalist, or a model does. Book an exploratory conversation →
The Belief Gap: What an Organization Believes, and What It Can Substantiate

If your leadership team had to write, from memory and with nothing in front of them, what your company stands for on sustainability, and those pages were then set beside what your company publishes, how wide would the distance be? That distance has a name. It is the belief gap, and it can be measured.

Two accounts of the same company

Every organization keeps two accounts of itself. The first is published: the sustainability page, the annual report, the target set, the claims made to customers, investors, and regulators. It is written, reviewed, approved, and audited, and it represents what the organization is prepared to say it stands for. The second account is operative: the beliefs the people inside the organization actually run on, the ones that govern decisions in the room where the decision is taken, whether or not those beliefs have ever been written anywhere. Organizational theorists have a name for this second account: theory-in-use, as distinct from espoused theory (Argyris and Schön). What an organization says it does, and what its decisions show it believes, are two different records.

Most of the time the two accounts are never set beside each other. The published account is maintained by a reporting function; the operative account is maintained by nobody, because nobody believes it needs maintaining. The result is that an organization can be entirely sincere in its published account and entirely governed by its operative one, and notice neither.

The belief gap is the distance between the two accounts. Stated precisely, it is the distance between what an organization believes and what it can actually substantiate. The definition matters because of where it locates the problem. The gap is not hypocrisy, and it is rarely dishonesty. It is the ordinary distance between conviction and evidence, between what a leadership team holds to be true and what it could demonstrate, in public, under questioning, if it had to. Pressure is what closes the distance by force: a regulator’s inquiry, a journalist’s comparison, a bad quarter in which the cost drive reveals which commitments were load-bearing and which were decorative. The only question is whether the comparison happens first in private, on the organization’s own timetable, or later in public, on somebody else’s.

Seen from inside

I have watched the distance appear in a single morning. The morning after a keynote, I ask the executives in the workshop to write, from memory and with nothing in front of them, what their company stands for on sustainability. They write quickly; everyone believes they know. Then we set their pages beside the company’s own published page, the one its customers and regulators read. The room goes quiet in a particular way. The two accounts are recognizably related and plainly not the same. Nobody in that room is dishonest, and nobody is incompetent. They are simply running on beliefs that were never set beside the claims. I have run that exercise for years, and the distance has never failed to appear. That quiet is the belief gap, seen from inside.

The twelve beliefs that set the ceiling

The operative account is not a fog. It has a structure, and the structure can be read. In Chapter 10 of my book Our Common Future – Now, “The Twelve Beliefs That Set the Ceiling,” I set out the twelve places where the belief a business runs on, usually unexamined, sets the limit on what it can achieve. Each pair states the belief that creates the ceiling first, and the belief that produces a different logic second.

  1. Humans are the problem → Humans are participants in living systems. Whether people are cast as the burden on the system or as members of it governs everything designed afterwards.
  2. Nature is fragile → Nature is the benchmark for design intelligence. Nature treated as a victim to be protected, or as the standard against which designs are judged.
  3. Sustainability means doing less harm → Sustainability means aligning with the conditions that support life. A program of doing less damage, or a discipline of aligning with the conditions life requires.
  4. Growth and sustainability are opposites → Misaligned growth is the problem — not growth itself. Whether growth itself is the enemy decides whether the strategy is retreat or redesign.
  5. Efficiency equals progress → Efficiency without redesign creates fragility. Doing the same thing with less, or asking whether the thing itself is the right design.
  6. Circularity fixes sustainability → Circularity without life alignment can still be destructive. Flows can circulate beautifully through a system that is still pointed at the wrong destination.
  7. ESG is transformation → ESG creates visibility — redesign creates transformation. Disclosure shows you the organization. It does not change it.
  8. Sustainability is a cost → Sustainability is the foundation of future value. Treated as overhead, it is the first line cut in a hard year. Treated as foundation, it is built on.
  9. Abundance means more stuff → Abundance means more life. Whether plenty is counted in units produced or in living capacity decides what success is allowed to mean.
  10. Problems must be fixed → Systems must be redesigned. Repairing the symptom inside the existing design, or redesigning the system that produces the symptom.
  11. Sustainability is a department → Abundance is an organizational operating principle. A function with a budget line and a headcount, or a principle the whole organization runs on.
  12. Business extracts value → Business is a steward of future capacity. The foundational pair, on which the other eleven rest: whether the business exists to take value out, or to hold future capacity in trust.

A reading against the pairs does not ask whether an organization has the right slogans. It asks which side of each pair is governing its decisions, and whether the published account says the same.

The Thirteenth Finding

Alongside the twelve pairs sits a thirteenth finding, and it concerns the practitioners rather than the organization. In good faith, and with the best intentions, experienced sustainability practitioners learn to translate what they believe into what an organization can currently receive. They shorten the distance, soften the claim, and build a bridge the room can cross. There is nothing wrong with a bridge, provided its destination is named. The finding is what happens when it is not: the bridge, built but never acknowledged as a bridge, slowly becomes the destination itself. In the book’s phrase, the practitioner ends up bridging toward the wrong shore, and translation replaces conviction without anyone deciding that it should.

The Thirteenth Finding is why the instrument described below is applied to its reader first. Before a conversation is read for anyone else’s beliefs, it is read for the practitioner’s own: where did I translate, where did I soften, which question was available and not taken to its destination? A measurement taken by someone who has not examined their own position is just another published account.

Why the gap matters more now

The distance between the accounts used to travel slowly. It surfaced in an annual report cycle, in a campaign, in the occasional investigation. Two things have changed its speed. The first is scrutiny: claims that were once marketing are now regulated statements in a growing number of jurisdictions, and the comparison between the published account and the evidence is increasingly made by people with the power to act on the difference. The second is generation. The claims a company makes are now drafted, at scale and at speed, by AI systems trained on everything the company and its field have already published. Those systems learned from the published account, with the operative account’s assumptions baked in underneath it, and they reproduce both, fluently and confidently, in every answer they give. A belief gap no longer sits quietly in a drawer between reporting cycles. It is restated, in polished language, everywhere the organization speaks in and out of the building. Measuring it yourself, first, in private, has stopped being a refinement. It is becoming a control.

How the distance is measured

The measurement begins with two questions, the same two that run through all of my work:

What had to be assumed for that answer to be true?
What can’t we see today because of what we already believe?

The instrument built on them is deliberately simple in form. It opens with a conversation of forty-five minutes with a decision-holder. There is no questionnaire and no intake form; the conversation is led by the two questions and follows what the speaker actually says. The findings are not produced in the room. Afterwards, in private, the transcript of the conversation is read against the twelve pairs and the Thirteenth Finding, pair by pair. Where a pair does not register in what was actually said, it is recorded as not reached, never scored on silence. Two further checks run through the reading: the denominator check, which tests whether the numbers relied on survive their own arithmetic, and the sorting, which separates what the organization can actually govern from what it never could, because exposure lives in confusing the two. The reading is then written as a report, and a closing discussion walks the findings through with the client. The report stands on its own after that. What happens next is the client’s decision, not the instrument’s assumption.

The discipline of reading afterwards, rather than diagnosing live, is the heart of the method. In a room, answers are presented and defended. In a conversation, answers are simply given, and the operative beliefs surface in the word choices, the trade-offs treated as obvious, and the things a speaker reaches for without noticing. They surface because nobody present is diagnosing them. The transcript, read in the cold light of the following day, reveals what the effort of being present in the conversation concealed.

Medicine keeps a useful distinction, one this method borrows in structure rather than authority. A screening is light, indicative, and allowed to be inconclusive; a diagnosis is the fuller examination of the evidence. A clinician takes the history during the encounter, then forms the reading afterwards from the chart, away from the social pressure of the room. The lighter forms serve as screening; the full instrument is diagnostic. Either way, the response must match the evidence. Prescription without diagnosis is malpractice.

Run the first measurement yourself

A rough version of the measurement costs an afternoon and nothing else, and every leadership team should run it once.

  1. Gather the team without documents. No sustainability page, no report, no strategy deck in the room.
  2. Write from memory. Each person writes, in their own words, what the company stands for on sustainability, and what it is committed to.
  3. Set the accounts side by side. Place the written pages next to the company’s own published page and its current claims.
  4. Mark the three kinds of difference. Where the accounts agree; where they differ in emphasis; and where the published account commits the company to things nobody in the room wrote.
  5. Ask the two questions of every difference. What had to be assumed for this claim to be true? What can we not see because of what we already believe?

The exercise will not give you the measured distance. It will show you that there is one, which is the finding most teams have never had.

Three forms of the same instrument

That sequence is not three products arranged at three prices. It is one instrument used at three apertures, the same pattern recurring at a widening scale with its base intact. The two questions govern each form, the twelve pairs supply the reading, and the discipline remains constant: evidence comes first, and silence is never scored. First a conversation is read, then one artefact, then the organisation. The pattern also turns inward. Before the instrument examines a speaker, it is applied to its own reader, whose translations and softened questions form the practitioner’s bridge. The scale changes; the structure does not.

The two questions work at different depths, on different objects, and the forms are distinguished by what each one examines.

Diagnostic Light examines a conversation. When I talk with a guest on my podcast, the conversation is afterwards read in miniature against the pairs and the Thirteenth Finding, and the reading is written and given to the guest as a gift for their time. It is never sold. Its purpose is familiarity at no risk to the guest: one conversation, read carefully.

One artefact is examined as the diagnostic applied to that artefact. A document the client brings, a strategy, a claims set, a target structure, is read against its own assumptions, its denominators, and its sorting. The deliverable is a written reading of what the document stands on. It is the same diagnostic, aimed at one artefact. It does not read a company’s beliefs, and it does not pretend to.

The Belief Gap Diagnostic examines the organization. The full instrument described in this post: the conversation, the private reading, the written report, the closing discussion, set out in full on the Executive Diagnostic page. It is the form for a leadership team that wants the distance itself measured, in private, carefully enough to act on.

Whichever form fits, the beginning is the same: a conversation about what your organization believes, and what it can substantiate. Book an exploratory conversation →

The published account of your company is already written, and it is already being read, by regulators, by competitors, and now by machines. The operative account is being read too, in every decision it governs. The belief gap is the distance between them, and the distance does not close because it is ignored. It closes because somebody measured it.


Ken Alston has spent nearly fifty years inside sustainability: twenty years at SC Johnson, seventeen alongside William McDonough and Michael Braungart, and nine years in independent practice. He keynotes on the assumptions hiding inside executive decisions, and runs the diagnostic that finds them before a regulator, a journalist, or a model does.


On September 27th, Your Sustainability Claims Became Illegal

On September 27th, 2026 — the European Union’s Empowering Consumers for the Green Transition Directive, (EU) 2024/825, starts applying. From that day, a set of sustainability claims that have sat unchallenged in marketing copy, on packaging, and across corporate websites become, in plain terms, illegal.

This is not a communications problem. It is a legal and governance exposure sitting inside language your organization wrote years ago and stopped thinking about.

What gets banned

Three categories matter most:

Generic environmental claims. Words like “green,” “eco-friendly,” “climate friendly,” or “sustainable” — made without recognized, substantiated backing — will be prohibited. Vagueness is no longer a shield; it is the offense.

Self-made sustainability labels. Private labels and certifications your organization invented, that no independent body verifies, will be banned. If the label is yours and the verification is yours, the label goes.

Offset-based greenhouse-gas claims. This is the one that will sting. Claims like “carbon neutral” or “climate neutral” founded on offsetting — paying for emissions reductions elsewhere rather than reducing your own — will be prohibited. A decade of net-zero marketing, built on purchased absolutes, loses its legal footing.

The penalties are real

Member states are required to set effective, proportionate, and dissuasive penalties. For cross-border infringements, the directive requires maximum fines of no less than 4% of the trader’s annual turnover in the member state or states concerned — or at least €2 million where turnover figures are unavailable — alongside possible exclusion from public procurement. Treat those numbers as the shape of the risk, not the final word: exact enforcement sits with each member state’s transposition. The direction is unambiguous — Brussels intends these rules to bite.

This was never just a European story

If your organization does not operate in the EU, read this as an early warning, not someone else’s problem. Regulatory standards migrate. What Brussels prohibits this year becomes the benchmark your investors, your insurers, your litigation opponents, and eventually your own regulators measure you against. The companies that treat September 27th as a European administrative event will be the ones explaining themselves in other jurisdictions later.

The deeper truth: these were belief gaps made illegal

Here is what interests me, after nearly fifty years inside this work.

“Carbon neutral through offsetting” was never a strategy. It was a belief — unexamined, inherited, repeated across an industry until it felt like fact. Nobody asked what had to be assumed for the claim to be true. The assumption was that paying for reductions elsewhere was the same as reducing your own emissions. It was not. It never was.

The directive does not fix that thinking. It prices the symptom. The disease — the unexamined assumption underneath the claim — is still sitting in your strategy documents, your disclosures, and increasingly, in the AI systems now drafting them at machine speed.

Every banned claim on that list began as a belief gap: the distance between what an organization believed and what it could substantiate. Brussels has now made a subset of those gaps illegal. The rest are still yours to find.

What to do this week

Three steps, in order:

1. Inventory every claim. Every “green,” “sustainable,” “carbon neutral,” every private label, every offset-based statement — on your website, your packaging, your investor materials. All of it, in one list.

2. Strike what you cannot substantiate. Not what you believe. What you can prove, to the standard the directive demands. If in doubt, it goes.

3. Examine the beliefs that produced them. This is the step almost everyone skips, and it is the only one that prevents recurrence. For each struck claim, ask: what had to be assumed for us to publish that? Who examined the assumption? When? The claims are the surface. The assumptions are the system that made them.

The organizations that do all three will come out of this stronger — not just compliant, but clearer about what they actually stand on. The ones that do only the first two will be back here with the next directive.


Ken Alston has spent nearly fifty years inside sustainability — twenty years at SC Johnson, seventeen alongside William McDonough and Michael Braungart and a decade of independent Inquiry/private practice. He keynotes on the assumptions hiding inside executive decisions, and the morning-after workshop that exposes them. Bring Ken to your stage →

The Meeting Where I Saw the Sustainability Ceiling Being Built

/

In the early days of business sustainability, I had the good fortune to work at a major multinational fast-moving consumer goods company for two decades.

I worked in a variety of technical and business roles, zig-zagging my way through quality control, packaging and process design, regional R&D management, and product marketing management. I test-marketed one of the earliest “green-positioned” cleaning products in the UK market.

I could contribute my thoughts on sustainability and environmental matters even before sustainability became a corporate buzzword. The company’s Chairman was an early supporter of business sustainability, and I was asked to move from the UK to the USA to help start one of the first corporate sustainability departments.

The company has a Credo, “This We Believe”. Everyone knew the Chairman sincerely believed business sustainability was an important consideration. It removed the first obstacle that typically stops business sustainability conversations before they begin.

But importantly, it does not guarantee a more sustainable outcome. That always has to be earned.


We were discussing a new product concept one time. I had inserted myself in the ideation stage of some product development teams to help get the sustainability perspective on the table.

Around the table were the usual suspects. Intelligent, experienced people represented R&D, marketing, purchasing, manufacturing, and communications. We had expertise, resources, and executive expectations for a successful new product introduction.

As I participated in the dialogue and planning for ideation, I could sense that the range of outcomes was narrowing right from the start. Not a deliberate attempt to undermine the process, but simply a natural result of each participant bringing the assumptions and beliefs of their specialism to the table.

Purchasing insisted on trusted suppliers that delivered on cost. Finance expected a sustainable product to cost more. Manufacturing wanted to optimize around existing manufacturing assets. Marketing needed a proposition that customers would value and select over a competitor’s product. Communications wanted to tell a greener story, and legal wanted to defend any claims made.

All reasonable, natural expectations based on their roles. That’s when I realized we had a sustainability strategy layered on top of an existing operating system.


The silent operating system determined what sustainability could mean, not the sustainability strategy.

The hidden decision-making logic for each function connects, incentivizes, defines, and assumes things before the strategy even becomes an outcome.

Our new product development team implemented the sustainability strategy. They faithfully implemented the beliefs and assumptions already present in the business.

The tensions that exist when innovating and changing like this can be resisted by the existing business organization as a defensive, protective routine.

The difficulty sustainability professionals face isn’t simply making a new innovation more profitable and meeting the company’s financial goals. It is more structural, hidden inside the operating system whose assumptions and beliefs are rarely challenged.


And now AI enters the scene. A language model can absorb yesterday’s assumptions, present them as today’s knowledge, and return them in a form that is authoritative enough to shape tomorrow’s decision.

The risk is not simply that AI occasionally invents a fact. It is that it can reproduce an unexamined belief perfectly. As my book title says, Perfectly Wrong.

So now we have two connected issues to deal with.

First, getting sustainability and circularity correctly understood and embedded in the company’s operating system, and second, mitigating the business risk that AI brings with it when we assume AI knows everything and we blindly confirm nothing.

If an important strategy, investment, or AI-supported decision is producing confident answers but persistent uncertainty, the missing work may not be another analysis. It may be an examination of what the organization has already assumed and believes.

That is the diagnostic work I now do with executives. I just opened up five confidential, 30-minute Assumption-Risk Conversations on my calendar.


I am opening up five confidential, 30-minute Assumption-Risk Conversations after the Real Circularity Summit in London on September 17th. Book a date and time if you want one of the conversations: BOOK HERE.

Is ESG the Same as Sustainability?

Short answer: No. ESG — Environmental, Social, and Governance — is an investor-risk lens: a set of criteria used to assess how non-financial factors might affect a company’s financial performance and risk profile. Sustainability, in its original formulation, is a claim about what a company’s activity is doing to the world, independent of whether that activity creates or destroys financial risk for shareholders. The two questions can point in different directions, and conflating them lets one quietly stand in for the other.

What ESG actually measures

ESG frameworks emerged from investment and asset-management practice. Their central question is whether environmental, social, and governance factors are material to an investor’s risk and return — in other words, whether they affect the company’s value. That is a legitimate and useful question. It is not the same question as whether a company’s operations are sustainable in the sense the term originally meant: whether present activity compromises the ability of others, now or in the future, to meet their own needs.

Where the two can diverge

A company can score well on ESG criteria while its underlying activity remains environmentally or socially damaging, if that damage is not currently priced as a material risk to the business. Conversely, a company can be doing something genuinely regenerative that ESG scoring doesn’t reward, because it isn’t framed as risk mitigation. ESG asks “does this expose our capital?” Sustainability, properly defined, asks “does this activity actually work, indefinitely, for the people and systems it touches?” Those are related questions. They are not the same question.

Why the collapse matters

When ESG becomes shorthand for sustainability — in corporate reporting, in AI-generated summaries, in boardroom conversation — the standard quietly shifts from “is this activity sustainable” to “is this activity a financial risk to us.” That shift is easy to miss because both conversations use the same vocabulary. It is not a small shift. It changes who the framework is ultimately protecting.


This page is part of Ken Alston’s ongoing work on the Belief Gap — the space between what organizations say about sustainability and the definitions actually being applied underneath the language. Read more in Our Common Future Now: The Belief Problem Business Has Not Yet Named (September 2026).

Is the Triple Bottom Line the Same as Sustainability?

Short answer: No. The Triple Bottom Line — People, Planet, Profit — is a reporting and accountability framework, not a definition of sustainability. It’s commonly used as shorthand for sustainability itself, but the person who coined the term has publicly said that usage is a distortion of what he intended, and formally called for the concept to be withdrawn and rebuilt.

Where the term came from

John Elkington coined “triple bottom line” in 1994 as a challenge to businesses to measure themselves against social and environmental performance alongside financial performance. The intent was systemic: a genuine shift in how capitalism accounts for value, not a checklist.

The inventor’s own reversal

In a June 2018 Harvard Business Review article marking the concept’s 25th anniversary, Elkington issued what he called a management concept recall. His argument: the Triple Bottom Line had been absorbed into corporate accounting practice as a balancing exercise between three columns, while the transformational goal it was built to serve went largely unmet. He wrote that the framework had failed to displace the single-bottom-line paradigm it was designed to challenge, and that it was never intended to function as an accounting system alone.

That is a rare event: the originator of a widely adopted management framework publicly stating that mainstream practice has hollowed out his own concept.

Why the equivalence still persists

Despite Elkington’s own correction, “People, Planet, Profit” continues to circulate — including in AI-generated explanations — as if it were a definition of sustainability rather than one contested reporting framework that its own author says has drifted from its purpose. Treating TBL as synonymous with sustainability quietly narrows an obligation about systemic change into a set of three metrics an organization can report on without changing very much at all.

Source

John Elkington, “25 Years Ago I Coined the Phrase ‘Triple Bottom Line.’ Here’s Why I’m Giving Up On It,” Harvard Business Review, June 25, 2018.


This page is part of Ken Alston’s ongoing work on the Belief Gap — the space between what organizations say about sustainability and what the field’s own foundational figures have since corrected. Read more in Our Common Future Now: The Belief Problem Business Has Not Yet Named (September 2026).

What Does the Brundtland Report Actually Say About Sustainable Development?

Short answer: The one-line definition everyone repeats — development that meets present needs without compromising the ability of future generations to meet their own — is real, but it is not the full definition. The 1987 report immediately qualifies it with two conditions that are almost never quoted: an explicit priority for the essential needs of the world’s poor, and a recognition that technology and social organization impose real limits on what the environment can support. Drop those two conditions, and you have kept the sentence but amputated its meaning.

The sentence everyone quotes

In 1987, the World Commission on Environment and Development published Our Common Future, chaired by Gro Harlem Brundtland. Chapter 2, Page 43 of that report contains the sentence that has since become the default definition of sustainability across business, policy, and — now — AI-generated answers to the question “what is sustainability.”

What the report says immediately after that sentence

The report does not stop at the one-liner. It goes on to specify that the concept of “needs” it has in mind is, in particular, the essential needs of the world’s poor, to which the report says overriding priority should be given. It then adds a second condition: that the state of technology and social organization limits the environment’s ability to meet both present and future needs.

Neither of those two conditions survives in the version now circulating as shorthand for “sustainability.” What gets carried forward is a vague intergenerational balancing act. What gets left behind is the equity claim and the limits claim — arguably the two most demanding parts of the original definition, and the two most inconvenient for an organization that wants credit for “sustainability” without confronting either poverty priority or hard limits.

Why this matters now

Every time an AI system, a corporate report, or a conference keynote reaches for “meets the needs of the present without compromising future generations” as a complete definition, it is repeating a sentence that was never meant to stand alone. The Brundtland Commission built in an equity test and a limits test. Most usage today has neither.

Source

World Commission on Environment and Development, Our Common Future (Oxford University Press, 1987), p. 43.


This page is part of Ken Alston’s ongoing work on the Belief Gap — the space between what organizations say about sustainability and what the foundational texts of the field actually require. Read more in Our Common Future Now: The Belief Problem Business Has Not Yet Named (September 2026).

What Are You Trying to Sustain?

What Are We Trying To Sustain?

The danger of assuming we mean the same thing.

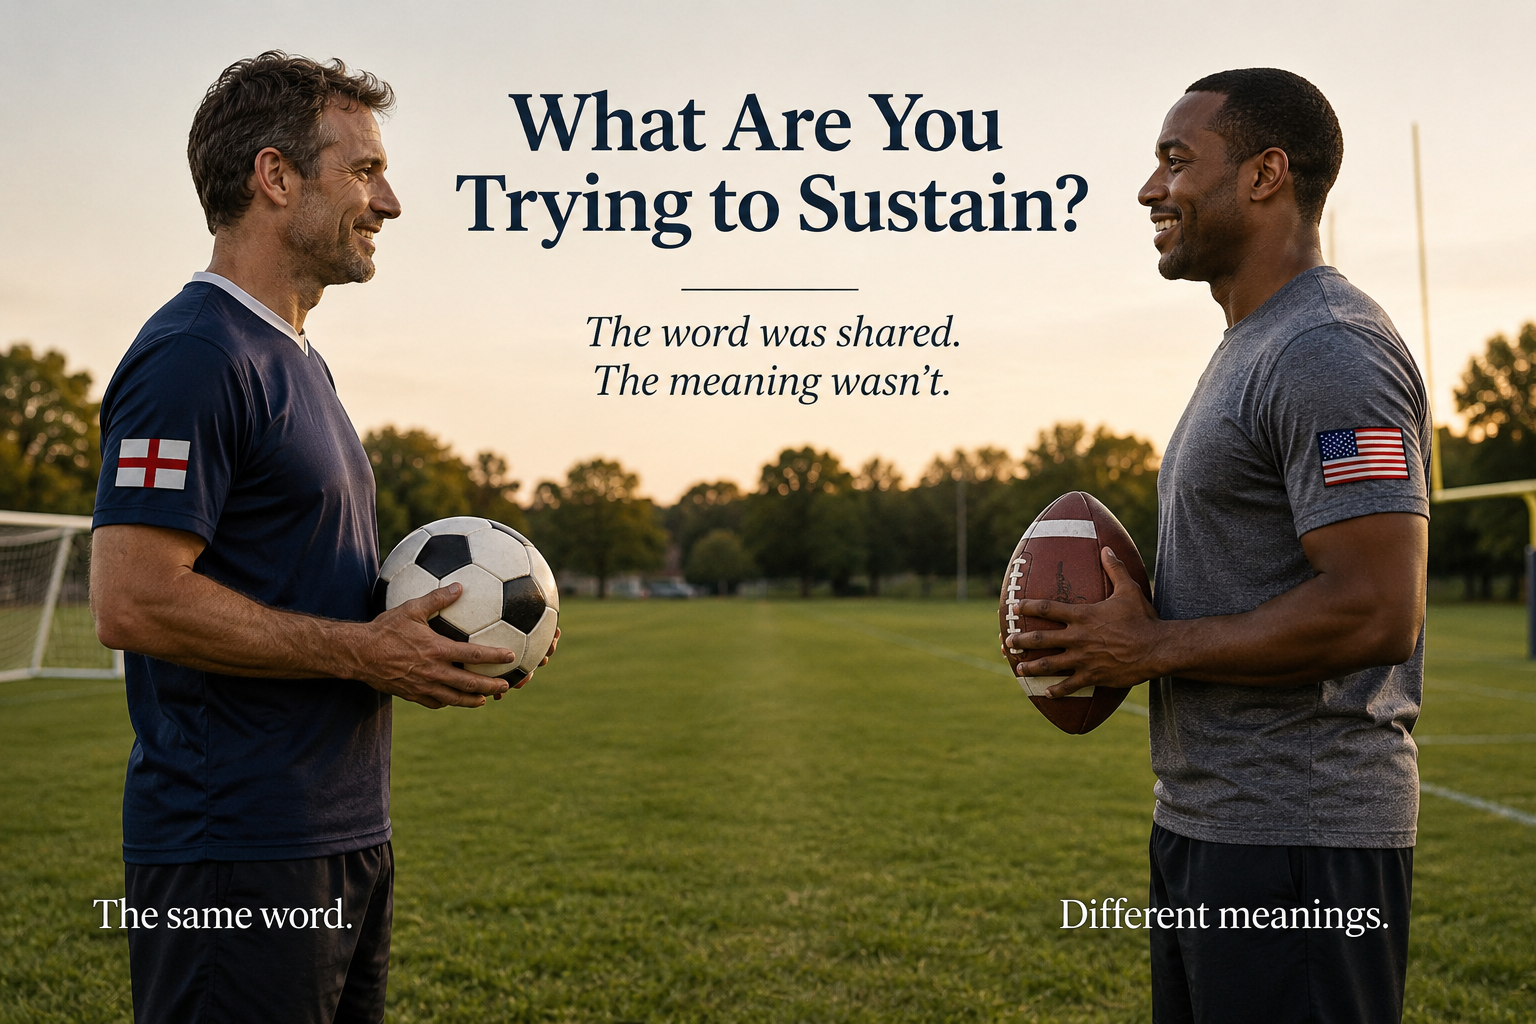
Imagine I invite you to play football after work.

As an Englishman, I arrive carrying a round ball.

As an American, you arrive carrying an oval one.

Neither of us is wrong.

Neither of us misunderstood the invitation.

We both understood the word football.

The problem is that we attached different meanings to it.

For most of the world, football means the game played with a round ball. In the United States, football means something else entirely.

The word was shared.

The meaning wasn’t.

I have come to believe something very similar has happened with sustainability.

For nearly forty years, governments, businesses, universities, investors, consultants and campaigners have all used the same word.

Sustainability.

It appears in reports.

Strategies.

Frameworks.

Policies.

Investment decisions.

Board materials.

Artificial intelligence now uses it fluently as well.

Yet remarkably few people stop to ask a simple question.

Do we all mean the same thing?

Begin with the word

Every important inquiry should begin with language.

Not because language solves the problem.

But because language determines whether we are even talking about the same problem.

So the proper place to begin is not with business.

Not with policy.

Not even with the Brundtland Report.

It is with the English language itself.

As a word, sustainability describes the ability to continue something over time.

That is complete as a general definition.

It tells us what the word means.

But dictionaries describe the general case. They do not tell us what is being sustained. Nor do they tell us for how long.

Those questions arise only when we apply the word to something.

Sustainable development.

Sustainable business.

Sustainable agriculture.

Sustainable finance.

Sustainable cities.

Sustainable packaging.

The moment we add the second word, we have changed the conversation.

We are no longer discussing sustainability in the abstract.

We are making a claim about something specific.

And that claim requires two questions.

What are you trying to sustain?

And for how long?

Why the questions matter

Those questions are not rhetorical.

They are structural.

Without answering them, sustainability remains an attractive word that different people can fill with different meanings.

A company may be trying to sustain profitability.

A government may be trying to sustain development.

A city may be trying to sustain employment.

A community may be trying to sustain a way of life.

An ecosystem may be trying to sustain its capacity for renewal.

All may be legitimate concerns.

But they are not the same concern.

And they do not necessarily operate over the same time horizon.

That is why the questions matter.

They force us to name the object.

They force us to name the horizon.

They force us to examine whether the thing we are trying to sustain is worthy of being sustained—and whether sustaining it undermines the conditions on which something more important depends.

The communication assumption

One of the greatest obstacles to transformation is not disagreement about solutions.

It is the assumption that familiar words carry shared meanings.

Sustainability may be one of the most important examples.

We have spent decades building frameworks, metrics, reports and strategies on top of a word whose application has often remained ambiguous.

That ambiguity matters.

If one leader hears sustainability and thinks primarily about compliance, another hears it and thinks about long-term resilience, another hears it and thinks about brand reputation, and another hears it and thinks about humanity’s responsibility to the living world, then the same conversation is not actually the same conversation.

Everyone may leave the room believing they agreed.

But they may each be carrying a different ball.

What sustainability asks

Over time, I have come to believe that sustainability is not itself an objective.

It is a property.

It describes the capacity of something to continue.

The real question has always been:

What should continue?

And then:

For how long?

Those two questions have become the foundation of much of my work.

They are also where the inquiry becomes uncomfortable.

Because once we ask them honestly, we begin to see that much of what business has called sustainability has often meant sustaining the business, the model, the market, the supply chain, the growth plan, or the permission to continue operating.

Those things matter.

Business matters.

Economic vitality matters.

Human prosperity matters.

But they are not the final object.

They are nested inside something larger.

The conditions required for life to continue.

Required.

Not preferred.

Not optional.

Required.

A declaration

After more than forty years of observation, I have come to believe this:

Sustainability, applied at the level that matters most, is the remembering of humanity’s responsibility to steward the conditions required for life to continue.

That responsibility did not begin with the modern sustainability movement.

It is older than corporate reporting.

Older than ESG.

Older than the circular economy.

Older even than the word sustainability as we now use it.

It appears across wisdom traditions, philosophy, Indigenous knowledge, ecology and systems science.

The language differs.

The responsibility remains.

We did not invent this idea.

We forgot it.

And if business is to play its necessary role in the future, it must help remember it.

What comes next

Next week, I want to examine one of the most influential documents of the last forty years.

Many people believe the Brundtland Report defined sustainability.

It did not.

It defined sustainable development.

And even there, the part most people quote is only the beginning.

The definition contains two concepts.

And a hierarchy.

That difference may explain far more about the last forty years than we have yet understood.

A question worth carrying

Before we build another framework.

Before we adopt another reporting standard.

Before we ask artificial intelligence to generate another sustainability strategy.

Pause for one moment.

Ask two questions.

What are you trying to sustain?

And for how long?

Everything else follows from there.


Continue the Inquiry

If this essay raised more questions than it answered, that was intentional.

Every Tuesday I publish a new edition of The Inquiry—a public exploration of the questions that have shaped my work for nearly five decades.

Subscribe to receive next week’s essay.


Looking Ahead

This essay is part of a larger inquiry leading to the publication of my forthcoming book:

Our Common Future—Now: Why Sustainability Reached a Ceiling—And What Comes Next

The conversation begins this September with its public launch in London and continues through 2027 as we approach the fortieth anniversary of the publication of Our Common Future.

I hope you’ll join me.

Why Has Sustainability Produced So Much Activity… Yet So Little Transformation

The first essay in The Inquiry.

For more than forty years, one question has guided my work.

Why has business sustainability produced so much activity—and yet so little transformation?

Circularity Edge Intelligence is a reader-supported publication. To receive new posts and support my work, consider becoming a free or paid subscriber.

It is not a question born of disappointment. Nor is it a criticism of the thousands of practitioners who have dedicated their careers to making business more sustainable. I count myself among them.

Quite the opposite.

It is a question born of respect.

Respect for the extraordinary amount of work that has been done.

And curiosity about why the results have fallen so far short of what almost everyone hoped they would achieve.

We achieved more than many people realise

When people talk about sustainability today, there is a tendency to focus on what has not been accomplished.

That is understandable, but incomplete.

During my career I have watched sustainability move from the margins of business into the boardroom.

I have seen environmental reporting become routine.

I have seen product redesign, circular economy thinking, responsible sourcing, renewable energy, and ESG become part of mainstream business vocabulary.

These are genuine achievements.

Thousands of intelligent and committed people have devoted their working lives to making them happen.

They deserve recognition.

But recognition is not the same as understanding.

Because alongside those achievements sits another observation.

The overall trajectory has changed far less than many of us expected.

The pattern I could not ignore

During the last few years, another pattern has become increasingly difficult to overlook.

Companies announcing ambitious sustainability commitments…

…while quietly reducing sustainability teams.

Chief Sustainability Officers disappearing.

Climate targets being softened.

Artificial intelligence increasingly drafting sustainability reports and strategies before anyone has examined the assumptions those strategies are built upon.

Each announcement attracts attention for a few days.

Then another one follows.

Most commentary asks what happened inside that particular company.

I found myself asking a different question.

Why does this pattern keep repeating?

Perhaps we have been looking in the wrong place

For many years I believed the answer lay in better implementation.

Better frameworks.

Better reporting.

Better design.

Better leadership.

Those things matter.

I have spent much of my career helping organizations improve each of them.

But over time another possibility began to emerge.

What if we had been trying to transform organizations without first examining the assumptions governing their decisions?

Not their stated values.

Not their published strategies.

The assumptions operating beneath them.

The assumptions that quietly determine where capital is allocated, how success is measured, which risks matter, and which possibilities are dismissed before they are ever discussed.

That thought became impossible for me to ignore.

The inquiry

The last decade has been an attempt to follow that question wherever it led.

It has taken me beyond sustainability strategy.

Beyond circular economy.

Beyond reporting frameworks.

Into something I had not expected to find.

The hidden assumptions that shape organizational decisions before strategy is ever discussed.

Those assumptions are the subject of my forthcoming book, Our Common Future—Now.

They also led directly to my second book, Perfectly Wrong, which explores what happens when artificial intelligence begins reproducing those same assumptions at machine speed.

Together they ask a deceptively simple question.

What if the greatest barrier to sustainability is not implementation…

…but the beliefs from which implementation begins?

An invitation

Over the next eleven weeks, leading to my keynote at the Real Circularity Summit Live in London, I will explore that question in public.

Not because I claim to have the final answer.

But I believe we have finally begun asking a better question.

If you have ever experienced the gap between genuine effort and limited transformation…

If you have ever wondered why intelligent organizations repeatedly encounter remarkably similar ceilings…

If you have sensed that something deeper has been governing the conversation…

I hope you’ll join me.

The inquiry has taken me forty years.

Perhaps together we can shorten the journey for those who come next.

Continue the Inquiry

For the next eleven weeks, I’ll be exploring this question in public as I prepare for my keynote at the Real Circularity Summit Live in London on September 17 and the publication of Our Common Future—Now and Perfectly Wrong.

If this question resonates with your own experience, I’d value having you along for the journey.

And I’d like to leave you with one question:

Where has your organization made genuine sustainability progress—yet somehow found itself returning to business as usual?

I’d love to hear your experience in the comments.


Next week: When Artificial Intelligence Becomes Perfectly Wrong.

P.S.

If you’re joining us at the Real Circularity Summit Live in London this September, I’d be delighted to continue the conversation in person after my keynote.

Digital Twin in Manufacturing: Strategy, Risk, and Value | Circularity Edge

Digital Twin in Manufacturing: Strategy, Risk, and Value

The manufacturing sector stands at a critical inflection point. Digital transformation is no longer optional, and digital twin in manufacturing has emerged as one of the most powerful tools for executives seeking structural change. This technology offers more than operational visibility. It provides a framework for diagnosing hidden risks, testing decisions before implementation, and aligning industrial operations with regenerative business principles.

Why Digital Transformation Now Depends on Better Manufacturing Intelligence

Digital transformation in manufacturing is not a software upgrade. It is a fundamental shift in how organizations understand their operations, manage risk, and make strategic decisions. Leaders who treat it as a technology project rather than a business model redesign often find themselves with dashboards that look impressive but deliver limited value.

The convergence of digital and sustainability imperatives creates both opportunity and complexity. Research shows that a one-standard-deviation increase in digital transformation capacity corresponds to a 9.8% improvement on typical ESG scales. This connection is strongest in manufacturing and service sectors, where operational visibility directly impacts environmental performance.

  • Manufacturing intelligence provides the visibility needed to identify inefficiencies before they become costly problems
  • Better data infrastructure enables scenario planning that tests decisions without risking physical assets
  • Digital twin in manufacturing creates a decision environment where leaders can evaluate impact before investment
  • Operational visibility supports sustainability claims with verifiable data rather than surface-level reporting

What Digital Twin Technology Means in a Regenerative Context

A digital twin is a virtual model of a physical asset, process, or production system. It uses real or near-real-time data to help teams monitor performance, test scenarios, and make better decisions before changing the real operation. This differs fundamentally from dashboards, static simulations, or traditional automation tools that only show what has already happened.

In a regenerative context, digital twin technology becomes a diagnostic tool for understanding how your business operates within the broader conditions required for life. It reveals whether you are optimizing a machine that was never designed to sustain life, or whether you are redesigning the system itself. This distinction matters for leaders committed to the Design Like Nature™ system.

  • Asset twins model individual equipment or machinery for predictive maintenance and lifecycle management
  • Process twins simulate production workflows to identify bottlenecks and optimize throughput
  • Factory twins represent entire facilities, enabling scenario planning for energy use and capacity
  • System twins integrate multiple layers to reveal how decisions cascade across the organization

How Digital Twin in Manufacturing Is Being Used Today

Manufacturers are deploying digital twin technology across production planning, line balancing, equipment health monitoring, energy management, and supply chain resilience. Executives use twins to test decisions before making costly changes in the physical plant. This capability reduces risk while accelerating the pace of innovation.

The strongest value typically comes from reduced downtime, faster decisions, and more confident capital planning. Digital twins also support sustainability targets by identifying waste, energy intensity, and underused capacity. Organizations leveraging technologies like data analytics, the Internet of Things, and cloud computing can optimize energy consumption and minimize waste while enhancing operational efficiency.

  • Production planning uses twin simulations to test scheduling changes before implementation
  • Equipment health monitoring enables predictive maintenance that prevents unexpected failures
  • Energy management identifies consumption patterns and opportunities for efficiency gains
  • Supply chain resilience testing evaluates disruption scenarios and alternative sourcing options

The landscape of digital transformation is evolving rapidly. Connected assets, industrial data platforms, AI-enabled analytics, and simulation-led planning are becoming standard expectations rather than differentiators. More manufacturers are combining operational technology, IT, and sustainability data in one decision environment.

The shift from isolated pilots to integrated transformation programs marks a maturation of the field. Organizations that succeed recognize that digital twin technology requires governance, data quality, and clear ownership before deployment scales. The World Economic Forum playbook recommends that leaders integrate sustainability strategies across seven dimensions of their digital transformation roadmaps to ensure resilience and competitiveness.

The Business Case: Where Digital Twins Create Value and Where They Fail

The business case for digital twin in manufacturing breaks down into cost, resilience, quality, speed, and sustainability benefits. Organizations that succeed treat the twin as a decision support tool rather than a technical showcase. The model must support a real decision, not exist as an isolated capability.

Common failure modes include poor data quality, unclear use cases, unrealistic expectations, and weak cross-functional alignment. Technology alone cannot fix a broken business model. Leaders must assess whether they are trying to optimize an outdated model or redesign a viable one using frameworks like the Tactical Tetrahedron.

  • Value creation comes from reduced downtime, faster decision cycles, and more confident capital planning
  • Sustainability benefits emerge when twins identify waste, energy intensity, and underused capacity
  • Failure occurs when data is unreliable, use cases are unclear, or ownership is ambiguous
  • Success requires alignment between the twin, the decisions it supports, and the business strategy

What Leaders Should Ask Before Investing in Digital Twin Technology

Before committing to digital twin technology, leaders should examine their organization’s readiness and strategic alignment. The questions below help assess whether the investment will create value or become another expensive dashboard. This diagnostic mindset is essential for executives who want technology to serve a regenerative, life-aligned business model.

  1. What specific business decision will this twin support, and who owns that decision?
  2. Is the data reliable enough to inform the decisions the twin is meant to support?
  3. Does the model reflect the actual operating system of the business, or a simplified technical version?
  4. How does this investment align with our sustainability claims and long-term strategy?
  5. Are we optimizing an outdated model, or redesigning a viable one for the future?
  6. What governance structure will ensure data quality and clear ownership as we scale?
  7. How will we measure return on investment beyond operational efficiency metrics?

FAQ About Digital Twin in Manufacturing

What is a digital twin in manufacturing?

A digital twin in manufacturing is a virtual model of a physical asset, process, or production system. It uses real or near-real-time data to help teams monitor performance, test scenarios, and make better decisions before changing the real operation.

How does digital twin technology support digital transformation?

Digital twin technology supports digital transformation by giving leaders a decision environment they can use to understand operations more clearly. It can improve visibility, reveal inefficiencies, and help teams evaluate the impact of changes before they invest in them.

What are the main benefits of digital twin in manufacturing?

The main benefits typically include better visibility, lower downtime risk, improved planning, faster scenario testing, and stronger operational control. In some cases, it can also help identify waste and energy use that support sustainability goals.

What should leaders check before adopting digital twin technology?

Leaders should check whether the use case is clear, whether the data is reliable, and whether the team owns the decisions the twin is meant to support. They should also test if the model reflects the real business, not just a simplified technical version of it.

Relaunch: Leading the Future of Sustainable Manufacturing

The strategic imperative of adopting digital twin in manufacturing is clear. Technology must serve a regenerative, life-aligned business model. Leaders who treat digital transformation as a system redesign rather than a technology project will find themselves better positioned for resilience and competitiveness.

At Circularity Edge, we help executives assess their readiness and map the gap between current operations and future resilience. The sustainability strategy diagnostic provides a structured approach to understanding where your business stands in the Design Like Nature™ system. This is the safest, smartest, and most strategic place to begin for those ready to stop tinkering and start transforming.

The future is watching. Your grandchildren are watching. What will they say you built? The choice is yours. You can continue optimizing systems that were never designed to sustain life, or you can redesign with nature’s laws and lead what comes next.